
KYC and AML are core requirements for any online casino that wants to operate in regulated markets. KYC helps an operator establish who a customer is and whether the customer is eligible to use the service. AML controls go further by helping identify, prevent, monitor, and report suspicious financial activity.
For an online casino, these controls cannot be limited to uploading an identity document during registration. A modern compliance program needs to connect customer identity, payment activity, source of funds, source of wealth, sanctions screening, PEP checks, transaction monitoring, risk scoring, and ongoing customer review.
The risk environment is also changing quickly. In September 2026, the Financial Action Task Force (FATF) published its first detailed recent assessment of risks across gaming and gambling, highlighting risks involving multiple accounts, mismatched identities and payment information, suspicious wagering patterns, mule accounts, complex ownership structures, virtual assets, and illegal operators.
For operators and iGaming technology providers, that means KYC and AML should be treated as part of the platform architecture—not as a separate compliance task added after development.
This guide explains what iGaming KYC and AML mean, how the process works, what information operators should collect, how risk-based monitoring works, what has changed in 2026, common AML red flags, technology requirements, and how SwissDice approaches compliance-ready iGaming software development.
What Is KYC in iGaming?
KYC, or Know Your Customer, is the process used to identify and verify customers and understand their risk profile.
For an online casino, KYC typically starts during registration and can continue throughout the customer relationship.
Depending on the jurisdiction and operator risk assessment, KYC may involve collecting and verifying:
- Full legal name
- Date of birth
- Residential address
- Nationality
- Contact details
- Identity document
- Proof of address
- Source of funds
- Source of wealth
- Occupation or income information
- PEP status
- Sanctions status
The exact information required depends on the market and the customer’s risk.
FATF’s standards, updated in June 2026, establish an international risk-based framework for combating money laundering and terrorist financing. Its customer-due-diligence principles include identifying and verifying customers, identifying beneficial owners where relevant, and applying appropriate ongoing controls.
KYC Is More Than Identity Verification
A common mistake is to treat KYC as a one-time document check.
A stronger approach is:
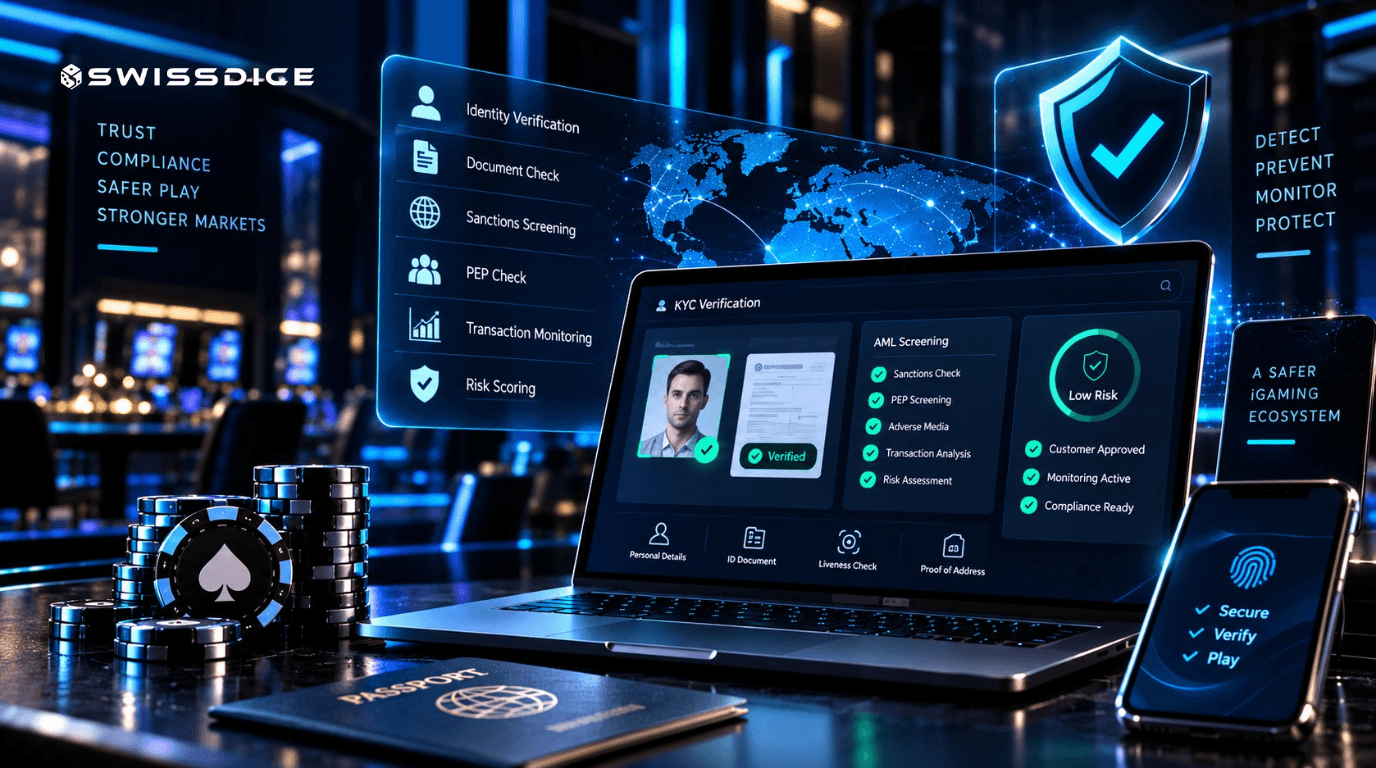
Identify → Verify → Assess Risk → Monitor → Update
A customer who passes identity verification at registration can still become higher risk later because of changes in payment behavior, transaction size, location, account activity, or other risk indicators.
That is why KYC and ongoing monitoring need to work together.
What Is AML in iGaming?
AML, or Anti-Money Laundering, is the broader framework used to prevent gambling services from being used to move, disguise, or legitimize criminal proceeds.
Depending on the jurisdiction, an operator’s AML/CFT program can include:
- Business-wide risk assessment
- Customer risk assessment
- Customer due diligence
- Enhanced due diligence
- Transaction monitoring
- Suspicious activity detection
- Suspicious transaction/activity reporting
- Sanctions screening
- PEP screening
- Source-of-funds checks
- Source-of-wealth checks
- Record keeping
- Employee training
- Independent testing
- MLRO or compliance oversight
- Third-party risk management
The need for effective controls has become more pronounced as online gambling becomes more digital, cross-border, and dependent on multiple payment channels.
FATF’s September 2026 gambling risk report specifically identifies online platforms, e-wallets, mobile money, virtual assets, illegal operators, and cross-border payment channels as areas where financial crime risks can arise.
KYC vs AML: What Is the Difference?
KYC and AML are closely connected, but they are not the same thing.
| KYC | AML |
| Establishes who the customer is | Prevents and detects financial crime |
| Verifies identity | Monitors financial and behavioural activity |
| Checks customer information | Assesses customer and transaction risk |
| Can include PEP and sanctions screening | Includes broader AML/CFT controls |
| Usually starts during onboarding | Continues throughout the relationship |
| Supports customer risk assessment | Supports detection and reporting of suspicious activity |
A useful way to think about the relationship is:
KYC tells the operator who the customer is.
AML helps the operator determine whether the customer’s activity presents financial-crime risk.
Why KYC and AML Matter for Online Casinos
Online casinos process large numbers of customer transactions and often operate across multiple payment methods, countries, brands, and digital channels.
The remote environment creates additional challenges because operators cannot physically meet customers.
The UK’s Gambling Commission continues to classify the remote casino sector as high risk for money laundering in its 2026 assessment. The regulator reported £5.0 billion in gross gambling yield for the remote casino sector for April 2024 to March 2025, including £4.2 billion from slots.
The same 2026 assessment highlights several current risks, including:
- Fraudulent identity documentation
- AI-generated identity documents and videos
- Mule accounts
- Multiple accounts
- Third-party payment methods
- Cryptoasset transactions
- Multiple payment methods
- Suspicious wagering patterns
- High-value live casino activity
- Higher-risk jurisdictions
The Commission also identified inadequate customer risk profiling, weak ongoing monitoring, inappropriate AML thresholds, insufficient source-of-funds scrutiny, and weak controls over linked or duplicate accounts as operator-side vulnerabilities.
For casino operators, effective KYC and AML therefore protect more than regulatory status. They help protect the operator’s payment relationships, customer accounts, financial systems, reputation, and licence.
How Does iGaming KYC Work?
A typical online casino KYC process can be divided into several stages.
1. Customer Registration
The customer provides core information during account creation.
At minimum, the platform should collect accurate information appropriate to the regulatory jurisdiction.
This stage is particularly important because poor data captured at registration can cause problems later.
In an August 2026 publication, the UK Gambling Commission warned remote operators against relying on incomplete information such as initials instead of full names, nicknames, commercial addresses instead of residential addresses, or middle names instead of forenames. It said operators should collect complete and accurate information and should not rely on overly permissive matching.
2. Identity Verification
The operator verifies that the customer exists and that the information submitted belongs to that person.
Verification methods may include:
- Government-issued ID
- Database verification
- Electronic identity verification
- Address verification
- Document authentication
- Biometric verification
- Liveness checks
The exact method should be appropriate to the jurisdiction and risk.
In the UK, remote operators must obtain and verify the customer’s name, address, and date of birth before allowing that customer to gamble. The Gambling Commission reiterated this requirement in August 2026.
3. Age Verification
The platform must confirm that the customer is legally permitted to gamble in the relevant jurisdiction.
Age verification should be integrated into onboarding rather than treated as an isolated compliance feature.
4. PEP Screening
The operator checks whether the customer is a Politically Exposed Person (PEP) or otherwise falls into a category requiring additional risk controls.
A PEP is not automatically a suspicious or criminal customer. PEP status is a risk factor that can require additional controls under applicable rules.
FATF’s guidance emphasizes effective identification and risk-based treatment of PEP relationships.
5. Sanctions Screening
Customer information should be screened against applicable sanctions and targeted-financial-sanctions lists.
Screening should not necessarily stop after registration. Ongoing screening may be needed because sanctions lists and customer circumstances can change.
6. Customer Risk Assessment
The operator assigns a risk level based on relevant factors.
Possible categories include:
Low Risk
Normal activity with no material risk indicators.
Medium Risk
Some additional risk factors require closer monitoring.
High Risk
Multiple risk indicators require enhanced due diligence and closer scrutiny.
Risk classification should be based on a documented methodology rather than simply assigning every customer the same score.
What Information Should an Online Casino Collect for KYC?
There is no universal checklist that applies to every licence, but a typical regulated casino may need some combination of the following.
Personal Information
- Full legal name
- Date of birth
- Residential address
- Nationality
- Country of residence
- Phone number
- Email address
Identity Evidence
- Passport
- National identity card
- Driving licence
- Other accepted identity documents
Address Evidence
Depending on the jurisdiction and risk:
- Utility bill
- Bank statement
- Government correspondence
- Other approved address evidence
Financial Information
For higher-risk situations:
- Source of funds
- Source of wealth
- Employment information
- Income information
- Bank or payment records
- Relevant supporting documents
The principle should be risk-based collection, rather than automatically asking every customer for the same volume of documents.
What Is Customer Due Diligence in iGaming?
Customer Due Diligence (CDD) is the structured process used to establish and verify customer identity, understand the relationship, assess risk, and monitor activity.
A practical iGaming CDD framework can include:
Standard CDD
Used for normal-risk customers.
Simplified Due Diligence
May be allowed in genuinely lower-risk circumstances where the applicable regulatory framework permits it.
Enhanced Due Diligence
Used when the customer, transaction, product, geography, or other circumstances present higher risk.
The FATF framework emphasizes proportionality and a risk-based approach rather than applying identical controls to every customer. The FATF Recommendations were most recently updated in June 2026.
What Is Enhanced Due Diligence for Online Casinos?
Enhanced Due Diligence (EDD) means applying additional measures when a customer or transaction presents higher money-laundering or terrorist-financing risk.
EDD may involve:
- Additional identity information
- Source-of-funds evidence
- Source-of-wealth evidence
- Additional payment information
- More detailed transaction review
- Senior management approval where required
- More frequent customer reviews
- More intensive transaction monitoring
The EU’s new Anti-Money Laundering Regulation specifically identifies additional measures for higher-risk relationships, including obtaining more information on customers, beneficial owners, source of funds and wealth, the reasons for transactions, and enhanced monitoring.
Source of Funds vs Source of Wealth
These terms are often confused.
Source of Funds
Source of funds means understanding where the money used for a particular transaction or activity came from.
For example:
Salary income → Bank account → Casino deposit
or:
Sale of an asset → Bank account → Casino deposit
Source of Wealth
Source of wealth concerns how the customer’s overall wealth was accumulated.
Examples can include:
- Employment
- Business ownership
- Investments
- Property
- Inheritance
- Sale of a company
- Other legitimate sources
A customer may have substantial wealth but use funds from a different source for a particular transaction.
Therefore, operators should not treat source of funds and source of wealth as interchangeable concepts.
The UK’s 2026 casino AML risk assessment specifically identifies failures to scrutinise source-of-funds documentation as a current operator vulnerability.
What Is Transaction Monitoring in iGaming?
Transaction monitoring is the process of examining customer transactions and behaviour for patterns that may indicate financial crime or other risk.
For an online casino, monitoring can include:
- Deposits
- Withdrawals
- Betting activity
- Payment-method changes
- Account-to-account relationships where relevant
- Chargebacks
- Wallet activity
- Crypto transactions
- Dormant-account activity
- Unusual changes in behaviour
A useful monitoring system should look at patterns, not just individual transactions.
For example, a single deposit may not look unusual. A repeated pattern of deposits, minimal gambling activity, multiple payment methods, rapid withdrawals, and multiple linked accounts may be much more significant.
Common AML Red Flags in Online Casinos
FATF’s new 2026 gaming and gambling risk indicators make this area especially relevant for operators.
Potential warning signs can include:
Multiple Accounts
One person controls multiple accounts under different identities or customer details.
Third-Party Payments
A customer funds an account using a payment method that does not appear to belong to them.
Identity and Payment Mismatch
The customer’s identity information does not align with payment information.
Minimal Gambling Followed by Withdrawal
A customer deposits funds, performs little or no meaningful gambling, and quickly withdraws.
Smurfing
A customer repeatedly makes smaller transactions in an apparent attempt to avoid detection or applicable thresholds.
Suspicious Wagering Patterns
The customer’s betting activity is inconsistent with their known profile or appears coordinated or unusual.
Mule Accounts
An account is operated or funded on behalf of another person.
Multiple Payment Methods
A customer rapidly moves between cards, e-wallets, bank accounts, and other payment channels.
High-Risk Geographic Connections
The account or transaction activity has links to jurisdictions presenting higher financial-crime risk.
False or Manipulated Documents
Documents appear altered, stolen, fabricated, or generated using increasingly sophisticated digital tools.
FATF’s September 2026 report specifically highlights multiple accounts, different identities and payment methods, suspicious identity documents, complex ownership structures, suspicious betting and transaction patterns, and criminal links involving operators or beneficial owners.
AI-Generated Fraud Is Now a KYC Risk
One of the most important developments for online casino compliance in 2026 is the increasing sophistication of identity fraud.
The UK Gambling Commission reported that it is seeing attempts to bypass customer due diligence using false documentation, deepfake videos, and AI-generated face swaps.
This changes the design requirements for identity verification.
A modern KYC system may need to evaluate:
- Document authenticity
- Facial similarity
- Liveness
- Device signals
- Registration data
- Database matches
- Velocity indicators
- Duplicate identities
- Account-linking signals
Why Document-Only KYC Is Not Enough
A forged document can look legitimate to a basic automated workflow.
A stronger process connects multiple signals:
Identity Document + Liveness + Customer Data + Device Signals + Risk Profile + Ongoing Monitoring
This does not mean that every customer should undergo the same level of friction. The verification process should be calibrated to the jurisdiction and the customer’s risk.
Crypto and AML for Online Casinos
Crypto-enabled casinos require additional attention because virtual assets can introduce different transaction and tracing characteristics.
FATF’s current virtual-asset standards require jurisdictions to regulate and supervise relevant virtual asset service providers and call for preventive measures such as customer due diligence, record keeping, suspicious transaction reporting, and secure transmission of originator and beneficiary information where the Travel Rule applies.
FATF’s 2026 gambling risk assessment also identifies cryptoasset transactions as a risk area for remote casinos.
For a crypto-enabled casino, AML architecture may therefore need:
- Blockchain transaction monitoring
- Wallet screening
- Address risk scoring
- Sanctions screening
- Transaction tracing
- VASP screening
- Travel Rule capabilities where applicable
- Source-of-funds analysis
FATF’s July 2026 virtual-asset update also reported that 83% of surveyed jurisdictions had passed legislation implementing the Travel Rule, compared with 73% in 2025, showing how quickly the regulatory environment is developing.
KYC and AML Rules: What Has Changed in 2026?
The regulatory landscape is becoming more detailed and more technology-aware.
FATF: Updated Standards in June 2026
FATF’s Recommendations were updated in June 2026 and remain the international baseline for national AML/CFT frameworks. FATF emphasizes a risk-based approach, customer due diligence, beneficial ownership transparency, and proportionate controls.
FATF: New Gambling Risk Indicators in September 2026
In September 2026, FATF published a dedicated assessment of gambling and gaming risks.
The report covers:
- Online gambling
- Illegal operators
- Payment channels
- Virtual assets
- Multiple accounts
- Identity fraud
- Mule accounts
- Suspicious wagering
- Complex ownership
- Cross-border activity
The report draws on contributions from more than 80 jurisdictions, industry bodies, and researchers.
This is one of the most important current reference points for operators reviewing their AML risk assessments.
UK Online Casino KYC and AML Rules
The UK is an important example of how detailed remote-gambling compliance requirements can become.
For UK-licensed remote operators:
- Customer identity must be verified before the customer is permitted to gamble.
- The identity process must establish that the customer exists and link the customer’s name, address, and date of birth to the same individual.
- Operators should not wait until withdrawal to request information that could reasonably have been obtained earlier.
For casino AML rules, UK regulations also use transaction thresholds. Current Gambling Commission guidance states that remote casinos must apply CDD measures when deposits or withdrawals connected with remote gambling reach €2,000 or more, including linked transactions, alongside other circumstances that trigger CDD such as a business relationship, suspicion, doubts about previously obtained information, or certain occasional transactions.
Importantly, the €2,000 threshold should not be interpreted as permission to ignore lower-value suspicious behaviour. The UK regulator’s 2026 risk assessment specifically warns about “smurfing” and inappropriate AML thresholds.
2026 UK Financial Risk Assessments
The UK is also introducing financial risk assessments in stages.
The Gambling Commission’s July 2026 update says the initial implementation targets the largest operators and customers with very high net deposits. The planned final thresholds are:
- Age 25+: more than £1,000 net deposits in a rolling 24 hours or more than £3,000 in a rolling 90 days.
- Under 25: more than £750 in a rolling 24 hours or more than £2,000 in a rolling 90 days.
The regulator says the implementation timetable is being developed with industry groups.
These financial risk assessments are not the same as AML checks, but they show the broader direction of remote gambling regulation: operators are increasingly expected to use customer financial information and behaviour to identify risk earlier.
EU KYC and AML Rules for Gambling Operators
The EU’s AML framework is undergoing a major transition.
Regulation (EU) 2024/1624, the new Anti-Money Laundering Regulation, treats providers of gambling services as obliged entities and sets out harmonised customer due diligence obligations.
The Regulation includes requirements covering:
- Customer identification
- Identity verification
- Beneficial ownership
- Purpose and intended nature of the relationship
- Targeted financial sanctions
- Ongoing monitoring
- Enhanced due diligence
- Record keeping
For gambling services, the Regulation provides for CDD when wagering or collecting winnings reaches €2,000 or the equivalent, including linked transactions.
Important 2026/2027 Date
The EU AML Regulation does not generally apply yet as of September 2026.
It is scheduled to apply from 10 July 2027.
This distinction matters for operators. Current national legislation remains relevant today, but businesses serving EU markets should already be preparing systems and compliance processes for the new harmonised framework.
The new Regulation also provides for five-year retention of relevant CDD and transaction records, subject to its detailed rules and potential extensions permitted by competent authorities.
Malta KYC and AML for Remote Gaming
Malta remains an important European iGaming jurisdiction, and its remote gaming AML framework provides another practical example.
Malta’s FIAU has stated that remote gaming operators apply a €2,000 threshold for CDD under the current PMLFTR framework, while minimum customer information and other controls may still be required before that threshold is reached.
Malta’s current supervisory direction is also significant. The FIAU’s 2026–2027 AML/CFT Supervisory Plan identifies areas including:
- Reporting obligations
- Risk-based controls
- Transaction monitoring
- Customer due diligence
- Source of wealth
- Source of funds
- Travel Rule obligations for crypto-asset service providers
In other words, operators should not design their compliance systems around one verification event. Ongoing monitoring is becoming increasingly important.
Australia: Online Gambling KYC and AML
Australia has also tightened online gambling customer-identification requirements.
AUSTRAC states that, from 29 September 2024, online gambling service providers must complete applicable customer identification procedures before creating an online gambling account or commencing a designated service. Providers must be reasonably satisfied that the customer is who they claim to be.
AUSTRAC’s current framework describes CDD as involving:
Identification + Verification + Risk Assessment + Ongoing Monitoring
and states that initial CDD generally needs to be completed before providing a designated service.
AUSTRAC also requires ongoing customer monitoring, including monitoring transactions and behaviour for unusual activity that may require a suspicious matter report.
US Casino AML Requirements
The United States requires a different analysis because gambling regulation is heavily dependent on state law, while federal Bank Secrecy Act obligations can also apply.
FinCEN states that casinos and card clubs that meet the applicable regulatory definition—including the federal gross annual gaming revenue threshold of more than $1 million—are subject to casino-specific BSA requirements.
Federal AML program expectations include:
- Internal controls
- Independent testing
- Employee training
- Designated compliance responsibility
- Procedures for customer identification
- Suspicious activity monitoring and reporting
- Recordkeeping
- Risk-based controls
FinCEN has also provided limited relief allowing suitable non-documentary identity-verification methods for online casino customers where appropriate, with suitability assessed according to risk.
Operators targeting US customers must therefore evaluate both federal requirements and the specific gambling rules of each state or tribal jurisdiction.
KYC and AML Compliance Workflow for an Online Casino
A practical compliance architecture can be structured as follows:
Registration
↓
Identity & Age Verification
↓
PEP & Sanctions Screening
↓
Customer Risk Assessment
↓
Account Approval
↓
Payment & Betting Monitoring
↓
Continuous Risk Reassessment
↓
EDD / Source-of-Funds Review Where Required
↓
Suspicious Activity Investigation
↓
Reporting / Restriction / Account Action
This workflow should be connected to the casino’s PAM, wallet, payment system, CRM, fraud engine, and back-office tools.
How to Implement KYC and AML in an iGaming Platform
KYC and AML should be integrated into the platform architecture from the beginning.
Player Account Management
The PAM should maintain:
- Customer profile
- Verification status
- Risk rating
- Screening status
- Document history
- Account status
- Linked accounts
- Transaction history
KYC API Integration
A casino can integrate specialist identity-verification services for:
- Document verification
- Database checks
- Address verification
- Facial verification
- Liveness
- Age checks
Third-party technology can support the process, but the operator remains responsible for its compliance decisions.
The UK Gambling Commission has explicitly warned that operators should not simply rely on third-party payment processors to conduct KYC or establish source of funds without additional scrutiny.
Sanctions and PEP Screening
Screening should be integrated with onboarding and ongoing compliance processes.
Transaction Monitoring Engine
The monitoring engine can process:
Deposits + Withdrawals + Betting + Payments + Account Behaviour
and compare that activity against rules and risk models.
Case Management
Suspicious alerts should enter a compliance workflow where authorized staff can:
- Review customer data
- Review transactions
- Request documents
- Record decisions
- Escalate cases
- Apply restrictions
- Maintain audit trails
Reporting
The platform should make it possible to generate regulatory and internal reports without manually reconstructing a customer’s activity.
Machine Learning and Automated AML Monitoring
Automation can help compliance teams process large volumes of customer activity, but automated systems need appropriate governance.
Potential uses include:
- Transaction anomaly detection
- Account-link analysis
- Duplicate-account detection
- Risk scoring
- Behavioural analysis
- Document fraud detection
- Network analysis
- Payment-pattern analysis
- Alert prioritisation
However, automation should not become a black box.
The EU’s upcoming AML framework includes requirements concerning human involvement in certain automated decision-making contexts and requires obliged entities to be able to demonstrate that their measures are appropriate for identified risks.
For an operator, the practical objective should be:
Automation for scale + human review for material decisions
How Should an Online Casino Handle Suspicious Activity?
When a monitoring system generates an alert, the response should be risk-based.
A typical workflow is:
Detect
An unusual transaction or customer behaviour is identified.
Review
The compliance team reviews customer history and supporting information.
Investigate
Additional information may be requested where appropriate.
Risk Assess
The operator determines whether the activity is consistent with the customer’s known profile.
Decide
Possible outcomes can include:
- No further action
- Increased monitoring
- Request for additional information
- Enhanced Due Diligence
- Transaction restriction
- Account restriction
- Relationship termination
- Regulatory reporting
Where a suspicious transaction/activity report is required, operators must follow the reporting rules of the relevant jurisdiction and avoid improper customer disclosure or “tipping off.”
KYC and AML Record Keeping
Compliance records should be organized so that the operator can demonstrate:
- What information was collected
- How identity was verified
- What risk factors were considered
- Why a customer received a particular risk rating
- What monitoring occurred
- Which alerts were generated
- What decisions were made
- What reports were submitted
- Who approved significant decisions
In the UK, Gambling Commission guidance states that identification and verification records and supporting records should generally be retained for five years after the business relationship ends, subject to stated exceptions.
The EU AML Regulation scheduled for application from July 2027 also provides for five-year retention of specified AML records, with detailed rules covering extensions and deletion.
Retention periods must always be implemented according to the actual jurisdiction and applicable data-protection law.
Data Protection and KYC
KYC creates a large amount of sensitive personal information.
A casino may hold:
- Identity documents
- Addresses
- Financial information
- Transaction history
- Risk assessments
- Biometric information
- Screening results
Therefore, the compliance architecture should also address:
- Data minimisation
- Access controls
- Encryption
- Secure storage
- Data retention
- Deletion procedures
- Vendor access
- Audit logs
- Cross-border data transfers
- Incident response
The objective is not to collect the maximum possible amount of information.
The objective is to collect appropriate information, protect it, use it for legitimate compliance purposes, and retain it only as required.
Common KYC and AML Mistakes Made by Online Casino Operators
Treating KYC as a One-Time Event
Passing onboarding does not eliminate future AML risk.
Waiting Until Withdrawal
The UK Gambling Commission has specifically criticized situations where operators only raise identity questions when customers attempt to withdraw. In its August 2026 reminder, the Commission said information that could reasonably have been requested earlier should not first be demanded as a condition of withdrawal.
Using Weak Identity Matching
Accepting nicknames, incomplete names, commercial addresses, or overly permissive matching can weaken identity assurance.
Using One AML Threshold for Everyone
Risk does not depend solely on transaction value.
Ignoring Linked Accounts
Multiple accounts can hide relationships between customers and should be considered in the risk model.
Over-Relying on Vendors
Third-party KYC, payment, or screening providers can support compliance, but the operator remains responsible for its regulatory obligations.
Poor Source-of-Funds Controls
Payment information alone may not establish the legitimate origin of funds.
Weak Crypto Monitoring
Crypto deposits should not be treated as inherently anonymous or automatically low risk.
No Clear Audit Trail
A compliance decision without supporting evidence is difficult to defend during a regulatory review.
KYC and AML Compliance Checklist for Online Casino Operators
Before launching an online casino, review whether the platform can support:
Customer onboarding
- Complete customer information
- Age verification
- Identity verification
- Accurate address data
Screening
- PEP screening
- Sanctions screening
- Geographic risk checks
- Duplicate-account detection
Risk
- Customer risk scoring
- Product risk
- Payment-method risk
- Geographic risk
- Ongoing reassessment
AML
- Transaction monitoring
- Behaviour monitoring
- Source-of-funds checks
- Source-of-wealth checks
- Enhanced due diligence
- Suspicious activity workflow
Governance
- AML policies
- Compliance ownership
- MLRO responsibilities where applicable
- Staff training
- Independent testing
- Management oversight
Technology
- KYC APIs
- Screening APIs
- Risk engine
- Transaction monitoring
- Case management
- Audit logs
- Secure document storage
- Reporting
Data protection
- Encryption
- Access control
- Data retention
- Secure deletion
- Vendor controls
- Incident management
Why Risk-Based KYC and AML Is the Future of iGaming Compliance
Modern compliance is moving away from a simple model of:
“Verify ID once and approve account.”
A more realistic model is:
Customer Identity + Financial Behaviour + Transaction History + Payment Risk + Geographic Risk + Ongoing Monitoring
This is especially important as online gambling becomes more connected to digital wallets, cross-border payment systems, cryptoassets, mobile platforms, and increasingly sophisticated identity technologies.
FATF’s latest gambling report makes this shift clear: operators and regulators need to consider not only individual transactions but also behavioural, transactional, and operational indicators of financial crime.
How SwissDice Supports KYC and AML-Ready iGaming Platforms
SwissDice develops iGaming software with the platform architecture needed to integrate customer verification, payments, risk management, and compliance services.
Depending on the project scope, a SwissDice-powered platform can integrate:
- KYC and identity verification
- Age verification
- PEP and sanctions screening
- AML transaction monitoring
- Risk scoring
- Source-of-funds workflows
- Source-of-wealth workflows
- Payment gateway integration
- Crypto payment integration
- Player Account Management
- Wallet systems
- Fraud detection
- Linked-account detection
- Admin dashboards
- Compliance reporting
- Audit trails
- Custom reporting
The technology layer can be designed around the operator’s chosen jurisdiction and regulatory requirements.
For a new casino, the important step is to define the jurisdiction, licence, customer base, payment methods, risk profile, and compliance obligations before the platform architecture is finalized.
Final Thoughts
iGaming KYC and AML are not simply compliance checkboxes. They are part of the operating infrastructure of a modern online casino.
A reliable compliance program needs to answer four fundamental questions:
Who is the customer?
Where did the customer’s money come from?
Does the customer’s activity match their known profile?
Has anything changed that increases the customer’s risk?
In 2026, these questions are becoming more difficult because criminals can exploit multiple accounts, third-party payments, cryptoassets, cross-border platforms, sophisticated identity fraud, and AI-generated documentation.
At the same time, regulators are becoming more specific about what they expect from remote gambling operators. The UK’s 2026 risk assessment highlights identity fraud, mule accounts, crypto-linked funds, third-party payment methods, suspicious wagering and weaknesses in ongoing monitoring. FATF’s September 2026 report provides a broader international risk framework covering online gambling, illegal operators and multiple payment channels.
For operators, the practical response is to build KYC and AML into the product from the beginning.
That means connecting:
KYC → Risk Scoring → Payments → Transaction Monitoring → EDD → Case Management → Reporting
rather than managing each component as a disconnected system.
For iGaming businesses working toward a new casino platform, SwissDice can provide the technology foundation and integrations needed to build a compliance-ready product around the requirements of the intended market.
Frequently Asked Questions
What is KYC in iGaming?
KYC, or Know Your Customer, is the process used by an online gambling operator to identify and verify customers, assess relevant risk, and maintain appropriate customer information throughout the relationship.
What is AML in online gambling?
AML stands for Anti-Money Laundering. It refers to the policies, procedures, controls, monitoring, and reporting processes used to prevent gambling services from being exploited for money laundering and related financial crimes.
Is KYC mandatory for online casinos?
The exact requirement depends on the jurisdiction and licence. Many regulated markets require operators to verify customer identity and meet additional AML/CFT obligations. For example, UK remote operators must verify customer identity before permitting gambling.
What documents are required for casino KYC?
Requirements vary, but an operator may request a government-issued identity document, address information, and additional evidence such as source-of-funds or source-of-wealth documentation when required by risk or regulation.
What is Enhanced Due Diligence in iGaming?
Enhanced Due Diligence is additional scrutiny applied to customers, transactions, or relationships presenting higher financial-crime risk. It can include additional customer information, source-of-funds or source-of-wealth evidence, senior approval, and enhanced monitoring.
What are common AML red flags in online casinos?
Common indicators include multiple accounts, mismatched customer and payment information, third-party payments, unusual deposit and withdrawal patterns, minimal gambling followed by withdrawal, suspicious wagering, mule-account behaviour, and potentially fraudulent identity documents. FATF’s 2026 gambling risk assessment highlights these and other indicators.
Does accepting cryptocurrency change KYC and AML requirements?
Cryptocurrency can change the risk and compliance profile of a casino, but it does not automatically eliminate KYC or AML obligations. Crypto-enabled platforms may need additional wallet, transaction-monitoring, sanctions, and blockchain-analytics controls depending on the applicable regulatory framework.
How long should online casino KYC records be kept?
The retention period depends on the jurisdiction. For example, UK Gambling Commission AML guidance states that identification and supporting records should generally be retained for five years after the business relationship ends. The EU’s new AML Regulation also establishes five-year retention for specified records once it applies.
Can an online casino outsource KYC?
Yes, operators can use specialist KYC and compliance technology providers, subject to the applicable rules. However, outsourcing technology does not automatically outsource the operator’s regulatory responsibility. The UK Gambling Commission has specifically reminded operators that they cannot simply rely on third parties to perform KYC or source-of-funds checks without appropriate oversight.
How can AI help with KYC and AML?
AI and machine-learning techniques can assist with document fraud detection, anomaly detection, account-link analysis, behavioural monitoring, risk scoring, and alert prioritisation. They should be deployed with appropriate governance, human oversight, testing, and data-protection controls.
Can SwissDice integrate KYC and AML into an online casino platform?
Yes. SwissDice can integrate KYC, identity verification, sanctions and PEP screening, transaction monitoring, payment systems, risk controls, wallet infrastructure, reporting, and other compliance-related services into a custom iGaming platform based on the project’s target market and requirements.